This article contains affiliate links. If you click through and make a purchase, I may earn a small commission at no extra cost to you. Full disclosure.
If you have a low credit score and you're worried it means homeownership is out of reach, take a breath. It's not. Buying a home with bad credit is harder than buying with great credit, but it's absolutely possible. Many first-time buyers do it.
This guide covers what counts as "bad credit," which loan programs accept lower scores, the real costs of buying with poor credit, and the smartest strategies for moving forward.
What Counts as "Bad" Credit?
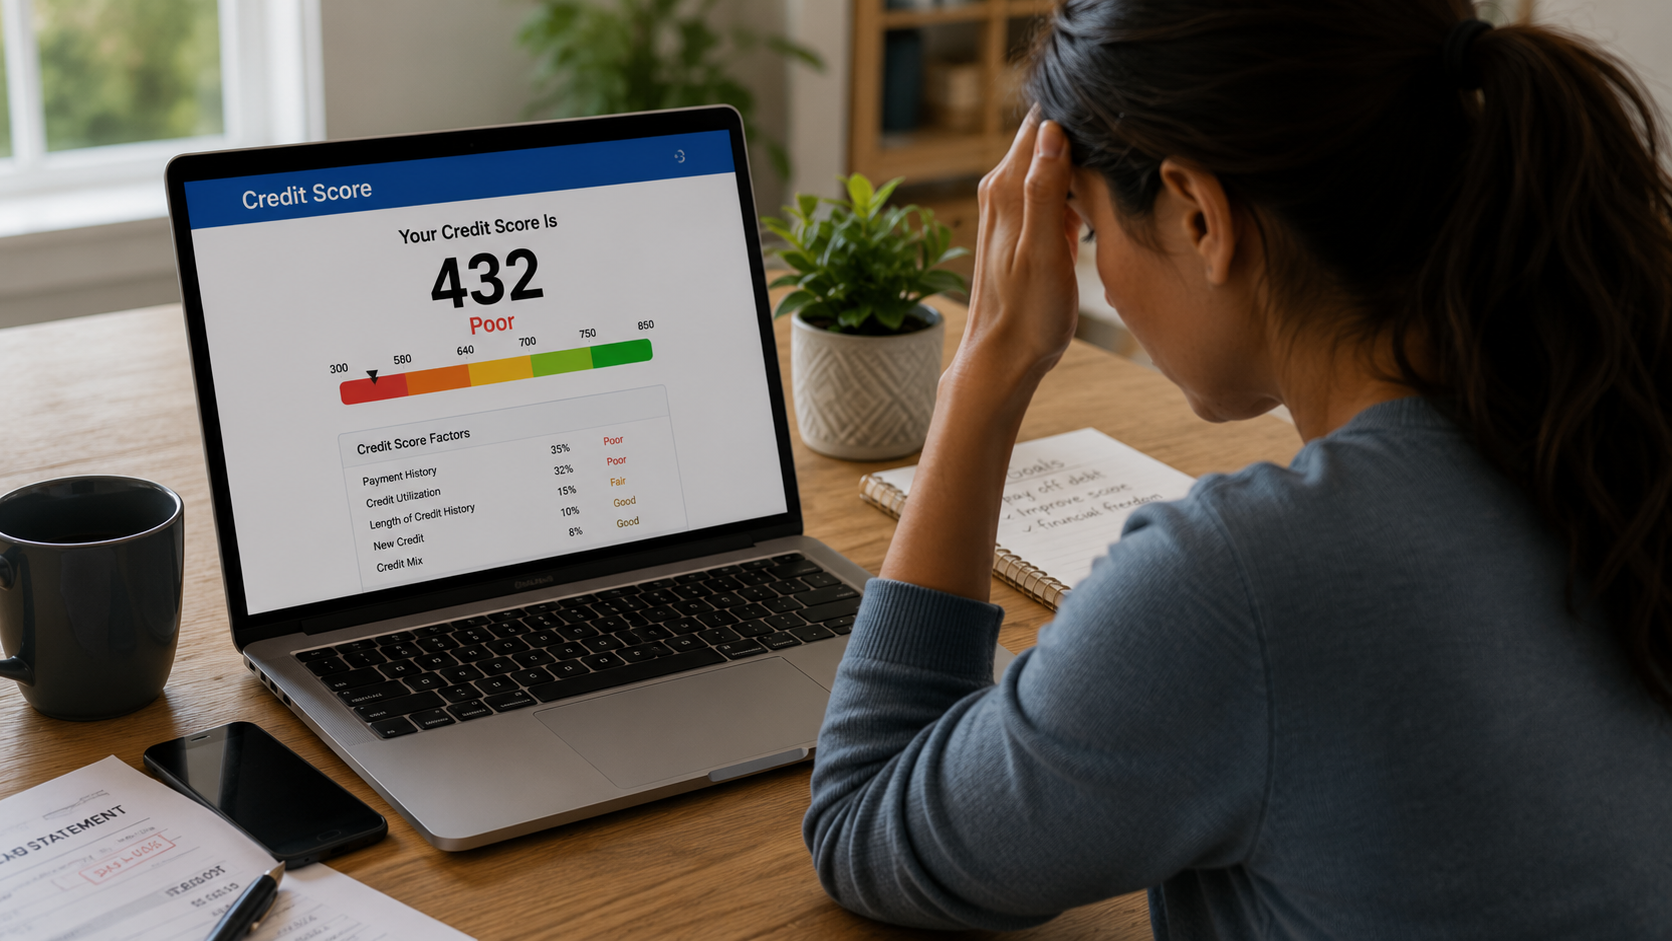
Credit score ranges generally break down as follows:
- Excellent: 740 and above
- Good: 670 to 739
- Fair: 580 to 669
- Poor: Below 580
For mortgage purposes, lenders typically consider anything below 620 to be "low credit." Anything below 580 puts you in the "subprime" category, which severely limits your options.
But here's what matters: even with a credit score in the 500s, you have options. Let's look at each one.
Loan Programs for Lower Credit Scores
FHA Loans: The Most Accessible Path
The Federal Housing Administration insures loans for borrowers who might not qualify for conventional financing. FHA loans are the most popular option for buyers with lower credit scores.
FHA credit requirements:
- 580 or higher: Qualify for 3.5% down payment
- 500 to 579: Qualify with 10% down payment
- Below 500: Not eligible
FHA loans require mortgage insurance, but they're often the only realistic path for buyers with credit challenges. The loan limits vary by county, ranging from $541,287 in low-cost areas to $1,249,125 in high-cost areas in 2026.
VA Loans: For Veterans and Active Military
If you've served in the military, VA loans offer remarkable benefits for buyers with lower credit:
- No minimum credit score set by the VA (though most lenders require 580 to 620)
- No down payment required
- No private mortgage insurance
- Competitive interest rates
VA loans are arguably the best mortgage option in the country if you qualify. If you have any military service, check your eligibility before exploring other options.
USDA Loans: For Rural and Some Suburban Properties
USDA loans are designed for buyers purchasing homes in eligible rural and suburban areas. Many areas you wouldn't think of as "rural" actually qualify.
- Credit score minimums typically 640, though some lenders go lower
- No down payment required
- Income limits apply
- Property must be in a USDA-eligible area
Check the USDA eligibility map for your target area before assuming you don't qualify. Many parts of Florida that feel suburban actually meet USDA requirements.
Conventional Loans with Lower Credit
Conventional loans typically require a 620 minimum credit score, but some programs accept lower scores. Fannie Mae's HomeReady and Freddie Mac's Home Possible programs still generally require a 620 minimum score, but they make qualifying easier at that level through lower down payments and reduced mortgage insurance when other factors are strong.
These loans require private mortgage insurance (PMI) for down payments below 20%, but PMI can be removed once you reach 20% equity, unlike FHA mortgage insurance. If you're weighing your choices, our guide to FHA vs conventional loans breaks down which fits different credit situations.
💡 Want the complete picture?
My free First-Time Homebuyer Guide covers everything you need to know before buying your first home: credit prep, financing, common mistakes, and the step-by-step buying process.
The Real Costs of Buying With Bad Credit
Lower credit scores don't just affect whether you can get a loan. They significantly affect what that loan costs you over time.
Interest rate impact:
On a $300,000 30-year mortgage, the difference between a 740 credit score and a 620 credit score can be 1.5% or more in interest rate. That translates to:
- About $275 more per month in payments
- About $99,000 more in interest paid over the life of the loan
Mortgage insurance:
Lower credit scores often mean higher mortgage insurance premiums, especially with conventional loans. FHA mortgage insurance is the same regardless of credit score, but it stays for the life of the loan in most cases.
Additional costs:
- Higher origination fees on some loans
- More expensive homeowners insurance
- Higher property tax escrow requirements
These costs are real, but they shouldn't necessarily stop you from buying. They should inform your decision and motivate you to improve your credit when you can.
Should You Wait to Improve Your Credit Before Buying?
This depends on your specific situation. Here's how to think about it:
Buy now if:
- You're paying high rent in an appreciating market
- Your credit issues are stable (not actively getting worse)
- You have a stable income and can afford the monthly payment
- You plan to refinance to a better rate once your credit improves
- The home will appreciate enough to offset higher financing costs
Wait to improve your credit if:
- You're in active financial distress
- Your debt-to-income ratio is also high
- You have no emergency savings
- You can realistically boost your score 50+ points in 6 to 12 months (see how long it takes to improve your credit)
- The local market is cooling
How to Strengthen Your Application
Even with bad credit, you can make yourself a stronger borrower:
1. Lower Your Debt-to-Income Ratio
Lenders look at how much of your monthly income goes to debt payments. The lower this percentage, the more attractive you are. Pay down credit card balances and avoid taking on new debt before applying for a mortgage.
2. Save a Larger Down Payment
A bigger down payment reduces the lender's risk and can offset credit concerns. It also reduces your loan amount, which means lower monthly payments.
3. Show Stable Employment History
Two years of consistent employment in the same field is the gold standard. If you've changed jobs, lenders want to see that you've stayed in the same industry.
4. Document Your Reserves
Having 3 to 6 months of mortgage payments in savings after your down payment makes you a much stronger borrower. Lenders love reserves.
5. Address Credit Issues Directly
Before applying, get a copy of your credit report and:
- Dispute any errors (yes, they happen often)
- Bring delinquent accounts current
- Pay down high-balance credit cards
- Don't close old accounts (length of credit history matters)
- Don't open new credit accounts before applying
- If your credit report has errors or you need professional help disputing negative items, a credit repair service can accelerate the process. Sky Blue Credit has been repairing credit since 1989 and can help you challenge inaccurate items on your report. See how Sky Blue Credit can help.
6. Consider a Cosigner
If you have a family member with strong credit willing to cosign, this can dramatically improve your loan terms. But understand: this person is taking on real risk, and your missed payments will hurt their credit.
Down Payment Assistance Programs
If your credit is challenging, your savings may also be limited. Florida has multiple programs that can help with down payments and closing costs:
- Florida Hometown Heroes Housing Program: Up to $35,000 for public service workers
- Florida Housing Finance Corporation programs: Various assistance for first-time buyers
- County-level SHIP funds: Local assistance varies by county
- Local lender programs: Many banks have proprietary first-time buyer programs
For a full rundown of what's available in the state, see our guide to Florida down payment assistance programs.
Most assistance programs require a homebuyer education course, which is generally a good idea anyway.
Working With the Right Lender
Not all lenders work the same way with lower credit scores. Some specialize in FHA and VA loans for buyers with credit challenges. Others won't touch a loan below 680.
When shopping lenders:
- Get quotes from at least 3 to 5 lenders
- Ask specifically about their experience with lower credit scores
- Compare not just interest rates but all fees
- Ask about their typical closing times
- Read reviews from buyers in similar situations to yours
A lender who specializes in lower-credit borrowers will often find approval paths that a traditional lender wouldn't.
The Refinance Strategy
Here's an underused strategy: buy now with the credit you have, then refinance once your credit improves. If you buy with a 620 credit score at 7.5% and your credit climbs to 720 over the next two years, you may be able to refinance at 6.25% or better, saving significant money on the loan you already have.
Rules of thumb for refinancing:
- Wait at least 6 to 12 months before refinancing (lenders often require this)
- Refinancing typically costs 2% to 5% of the loan amount in closing costs
- The new rate needs to be at least 0.5% to 1% lower to make refinancing worthwhile
Final Honest Take
Bad credit doesn't disqualify you from homeownership. It just means you need to be strategic, patient, and realistic about what you can afford.
The path forward usually involves:
- Understanding exactly what your credit looks like
- Identifying which loan program fits your situation
- Strengthening your overall application
- Working with the right lender
- Having a long-term plan to improve your credit and refinance later
Home ownership remains one of the best ways to build long-term wealth. Don't let credit challenges keep you sitting on the sidelines if buying makes financial sense in other ways.
The best time to start is by knowing exactly where you stand and what your options are. Pull your credit report, calculate your debt-to-income ratio, and start the conversation with a lender who specializes in lower-credit borrowers.
Frequently Asked Questions
What is the lowest credit score you can have to buy a house?
It depends on the loan. FHA loans allow scores as low as 580 with 3.5% down, or 500 to 579 with 10% down. Conventional loans typically want at least 620, and USDA lenders usually look for 640. VA loans set no official minimum, though most lenders prefer 580 to 620.
Can I buy a house with a 500 credit score?
Yes, but your options are narrow. An FHA loan can work with a score between 500 and 579 if you put down at least 10%. Below 500 you are not eligible for FHA financing and will likely need to rebuild your credit first.
Should I wait to improve my credit before buying a home?
It depends on your situation. Buying now can make sense if your credit issues are stable, your income is steady, and you plan to refinance once your score improves. Waiting makes more sense if you're in active financial distress, have a high debt-to-income ratio, or can realistically raise your score meaningfully in the next 6 to 12 months.
Does bad credit make a mortgage more expensive?
Yes. A lower score usually means a higher interest rate and, in many cases, higher mortgage insurance, which adds up over the life of the loan. That cost is one reason buyers often buy now and refinance later once their credit recovers.
If you're unsure where your number stands relative to these thresholds, start with our guide to what credit score you really need to buy a house.
Sources
The figures in this article were verified against the authoritative sources below. Rules, rates, and limits change over time, so confirm the current details with the agency or a licensed professional before you act.